Last reviewed: October 2026.
How much hail damage it takes to replace a roof comes down to how many functional hail hits an adjuster counts per 100 square feet (a 10-by-10 foot test square). About 8 to 10 hits per square is widely cited by adjusters and roofers as the point where slope or full replacement comes into play, but it is a rule of thumb, not a published standard: each carrier sets its own count in internal guidelines that it generally does not publish. Related: Partial roof replacement. Below the carrier’s count, you typically get repair only. Above it, the carrier is more likely to approve a slope or full tear-off and replace. Hail size matters too: stones under 1 inch rarely produce functional damage on architectural asphalt shingles, while 1.25-inch to 2-inch hail produces mat-fracture bruising that fails the test. The threshold also depends on the impact-resistance rating of your shingle (UL 2218 Class 1 through Class 4) and your carrier’s specific guidelines.
The short version
- A commonly cited rule of thumb is 8 to 10 functional hail hits per 100 square feet, but each carrier sets its own threshold and generally does not publish it.
- Hail under 1 inch rarely damages architectural shingles. Hail at 1.25 inches and up usually does.
- “Functional damage” means mat fracture, granule loss exposing the mat, or loss of weatherproofing. “Cosmetic” means dimples without mat fracture.
- Your policy sets the deadline to report a claim, and some states set one by statute (Florida: 1 year after the date of loss). Check your policy and file promptly.
- If an adjuster calls damage cosmetic only, request a re-inspection, get a written report from a licensed roofer, and consider a public adjuster.
How the Test Square Count Works: The 8 to 10 Hit Rule of Thumb
Insurance adjusters across the major carriers use a square-foot test to measure hail (for the full data set, see the 2026 Roofing Hail and Storm Loss Database) damage density. They mark off a 10-by-10 foot square on each roof slope, count the number of functional hail strikes inside it, and compare to their carrier’s threshold.
| Functional Hail Hits per 100 sq ft | Typical Carrier Decision | Approved Scope |
|---|---|---|
| 0 to 4 | Denied or repair-only | Cosmetic, no payout |
| 5 to 7 | Repair scope | Replace damaged shingles only |
| 8 to 10 | Slope replacement | Replace the entire affected slope |
| 10+ | Full roof replacement | Tear-off + new roof |
The table shows how the rule of thumb is usually described; it is not any carrier’s published guideline. The 8 to 10 figure is not set by any statute, regulation or published industry standard. Carriers set their own counts, which can be lower or higher, in internal guidelines they generally do not publish, and policy terms and state rules also shape the result. Ask the adjuster which threshold was applied and get the estimate and photos in writing.
The Adjuster Test: How Damage Is Measured
The adjuster’s playbook is consistent across carriers. Here is what happens when they show up:
- Walk-around inspection from the ground to find obvious damage and downed limbs.
- Ladder up to the roof. Check 4 test squares (one per major slope) by measuring with a chalk line or measuring tape.
- Use a soft chalk or lumber crayon to mark each functional hit found inside the test square.
- Photograph every marked hit with measurement reference.
- Check the soft metals: gutters, downspouts, AC condenser fins, soft-metal vent caps, window screens. Soft-metal damage corroborates hail event and size.
- Check for collateral: damaged screens, broken shingles, missing tabs, valley damage, flashing dents.
- Estimate hail size based on impact diameter on soft metals.
- Write the scope.
If you are present (and you should be), watch the test squares get drawn and counted. Take your own photos. Disagree on the spot if their hit count looks low.
Hail Size Matters: Marble, Golf Ball, Tennis Ball
Hail size correlates strongly with damage potential. The NOAA Severe Storms Reference Guide defines hail in standard size brackets, and the roofing industry uses those benchmarks too.
| Hail Diameter | Comparison | Damage to Architectural Asphalt |
|---|---|---|
| 0.5 inch | Marble | Cosmetic only, no mat fracture |
| 0.75 inch | Penny / dime | Borderline. Granule loss possible. |
| 1.0 inch | Quarter | NWS severe threshold. Functional damage possible. |
| 1.25 inch | Half dollar | Functional damage likely on standard shingles. |
| 1.5 inch | Walnut / ping pong ball | Functional damage on most shingles. |
| 1.75 inch | Golf ball | Severe damage. Often full replacement. |
| 2.0 inch | Egg / hen egg | Severe damage including deck. |
| 2.5 inch | Tennis ball | Catastrophic. Replacement guaranteed. |
| 2.75 inch | Baseball | Catastrophic. Often deck damage. |
| 4.0 inch+ | Softball | Total loss potential. |
The National Weather Service defines “severe” hail as 1 inch (quarter-sized) or larger. That is also roughly the threshold where standard 3-tab and architectural shingles begin showing functional damage. Class 4 impact-rated shingles can shrug off 1.5 to 2 inch hail with no functional damage at all.
UL 2218 Impact Resistance Ratings
The Underwriters Laboratories 2218 standard is the industry test for impact resistance. A steel ball is dropped from a measured height onto a shingle, and the shingle is graded based on whether it fractures.
| UL 2218 Class | Steel Ball Size | Equivalent Hail | Insurance Discount |
|---|---|---|---|
| Class 1 | 1.25 inch | 1 inch hail | Ask your carrier |
| Class 2 | 1.5 inch | 1.25 inch hail | Ask your carrier |
| Class 3 | 1.75 inch | 1.5 inch hail | Ask your carrier |
| Class 4 | 2 inch | 1.75 to 2 inch hail | Offered by some carriers; amount varies |
Class 4 shingles usually cost more than standard architectural shingles, so ask your roofer to price both in the same bid. Some carriers offer a premium discount for a UL 2218 Class 4 roof, but the size of the discount is set by each carrier and state and is not a fixed figure, so ask your carrier for its number before you decide. Whether the discount pays back the extra cost, and how fast, depends on that number and your premium. For state detail, see our impact-resistant shingle insurance discount by state guide. Major Class 4 products: GAF Timberline AS II, CertainTeed Landmark IR, Owens Corning Duration Storm, Atlas StormMaster Shake.
What Counts as “Functional Damage” vs “Cosmetic”
This is the single most contested point in any hail claim. The carriers, the contractors, and the public adjusters all use slightly different definitions, but here is the working consensus.
Functional damage (qualifies for replacement)
- Hail bruising: a soft spot in the shingle where the asphalt mat has fractured (felt as a soft, mushy dimple when pressed)
- Granule loss exposing the mat (black spots visible on the shingle)
- Cracks in the shingle mat radiating from a hit point
- Missing tabs caused by the impact
- Damage to seal strips that compromises wind resistance
Cosmetic damage (typically denied)
- Surface dimples with no mat fracture
- Granule loss without exposing the mat
- Minor scuffing
- Faded color from existing wear
- Algae streaks or moss
Some carriers in some states sell a “cosmetic damage exclusion” endorsement that lowers the premium in exchange for waiving cosmetic-only claims. Read your declarations page. If you have this endorsement, even slight-but-cosmetic damage is denied.
The 4-Square Test Adjusters Use
The adjuster typically tests four 10-by-10 squares, one per slope (north, south, east, west). Why four?
- It accounts for variation across the roof.
- It identifies whether damage is consistent (real hail) or sporadic (might be other causes).
- It surfaces wind-driven hail patterns, where one slope takes most of the impact.
If only one slope meets the carrier’s threshold but the others do not, you may get a single-slope replacement approval rather than full roof. If replacement shingles cannot match the existing roof, whether the carrier must extend the scope depends on your policy and state law. Florida, for example, requires the insurer to make reasonable repairs or replacement of items in adjoining areas when replaced items do not match in quality, color or size, unless the policy provides otherwise, per Florida Statutes section 626.9744. Some policies limit or exclude matching, so read yours.
Granule Loss Patterns from Hail
Hail granule loss has a distinctive look that differs from age-related shedding.
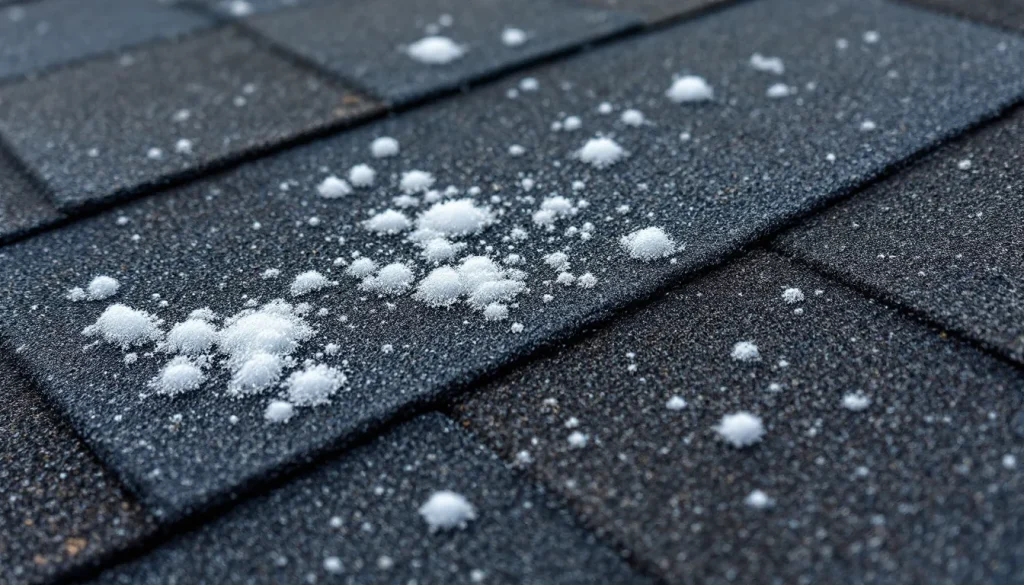
- Hail granule loss is concentrated in distinct circular spots roughly the size of the hail stone, with sharp edges. The exposed mat in the center is bright black.
- Age-related granule loss is diffuse, irregular, and concentrated along edges, ridges, and high-traffic foot paths.
- Mechanical granule loss (from tree branches, foot traffic, dropped tools) is in lines or smears.
Adjusters know these patterns. So do experienced roofing contractors. Photograph every distinct circular spot on the roof. They are your strongest documentary evidence.
Bruising vs Fracturing: The Invisible Damage
The single most overlooked form of hail damage is mat bruising that you cannot easily see from above. The granules look intact. The shingle looks OK. But the asphalt mat underneath has fractured, and the shingle has lost its weatherproof seal.
The test: a roofer presses firmly with a thumb on a suspected hit. A healthy shingle resists. A bruised shingle feels soft, mushy, almost like pressing into a marshmallow. Once you feel a bruise, you know what to look for, and you will find more across the roof.
Bruised shingles fail the same way fractured ones do, just on a delayed timeline. They leak within 6 to 24 months after the storm. This is why a documented hail event with bruising-but-no-cracking still typically qualifies for replacement.
Hail Map: Where Damage Is Most Common
The NOAA Storm Prediction Center keeps a database of every hail report. The hail belt runs through the central plains and Front Range states. The table lists the 10 states with the most reports of hail 1 inch or larger, ranked by the 2015 to 2024 annual mean.
| State | Mean annual hail reports, 1 inch or larger (2015 to 2024) | 2025 hail reports, 1 inch or larger |
|---|---|---|
| Texas | 1,072 | 1,302 |
| Kansas | 628 | 497 |
| Nebraska | 489 | 438 |
| Oklahoma | 420 | 637 |
| South Dakota | 376 | 267 |
| Colorado | 374 | 418 |
| Missouri | 319 | 480 |
| Minnesota | 306 | 205 |
| Iowa | 268 | 186 |
| North Dakota | 213 | 183 |
Source: Roofing Brief tabulation of the NOAA Storm Prediction Center severe weather database (final hail files, recounted October 2026). Counts are reports, not distinct storms. For every state and the full method, see our 2026 roofing hail storm loss database. If you live in one of these states, Class 4 impact-rated shingles are worth pricing, but whether they pay off depends on your carrier’s discount and the extra cost of the shingle. For scale, State Farm says it paid more than $5.6 billion in hail-related claims in 2025, led by Texas at $1.4 billion (State Farm newsroom, April 21, 2026).
Storm Date Matching: You Must Claim Within the Window
The deadline to report a claim is set mainly by your policy’s “duties after loss” section, and some states set a statutory deadline. In Florida, a new or reopened property claim is barred unless notice is given within 1 year after the date of loss, and a supplemental claim within 18 months, per Florida Statutes section 627.70132. Read your policy for its exact wording and report the damage as soon as you find it. Two things to lock down immediately after a hail event:
- Identify the storm date. Use the NOAA Storm Events Database or Hail Strike at hailstrike.com. You need the exact date and county for the carrier to match.
- Photograph everything within 72 hours. Damaged screens, dented gutters, bent flashing, vent caps, AC fins. Time-stamped photos prevent later disputes about when the damage occurred.
If you wait 18 months and then claim a hailstorm from 2 years prior, the adjuster will scrutinize whether the damage actually came from that event or from a later one not covered by your policy.
What If the Adjuster Says “Cosmetic Only”
This happens regularly. The adjuster walks the roof, draws their squares, counts 4 to 6 hits where you and your contractor counted 12 to 15, and writes “cosmetic damage, no payable claim.” Here is the playbook to challenge it.
- Request the adjuster’s report in writing, including their photos and notes.
- Get your roofing contractor‘s written report with photo evidence and a count of functional hits.
- Submit a formal request for re-inspection through your claims line. Most carriers will send a second adjuster, often a more senior one.
- Show up for the re-inspection with your contractor present. Two technical pros on the roof together produce better outcomes than a homeowner alone.
- If still denied, file with your state’s Department of Insurance. A regulator complaint often triggers another internal review.
- If still denied, hire a public adjuster (more on this below) or pursue appraisal under your policy’s appraisal clause.
Getting a Second Opinion: Public Adjusters
A public adjuster works for you, not the insurance company, and is usually paid a percentage of the claim payment. Some states cap that fee by statute. In Florida, for example, the cap is 10 percent of claim payments for claims made in the year after a governor’s state of emergency declaration and 20 percent for other claims (Fla. Stat. 626.854(11)(b)). Check your own state’s rules and get the fee in the written contract.
When a public adjuster makes sense:
- Your claim was denied outright but you have documented functional damage
- The settlement is less than half of your independent contractor’s estimate
- The adjuster missed a slope or excluded specific elements
- The carrier is dragging the process past 30 days with no clear reason
Public adjusters are licensed by state. Verify the license before signing. Avoid any “PA” who shows up uninvited after a storm. The reputable ones come from referrals, not door-knocks.
Insurance Carrier Differences: Hail Claim Criteria
Carriers do not publish the hit counts or scoping rules their adjusters apply, and outcomes vary by policy form, state, and the assigned adjuster, so a carrier’s reputation is a poor guide to your claim. Compare what your own policy says instead: whether the roof is settled at replacement cost or actual cash value, whether a cosmetic damage exclusion or a roof payment schedule applies, the size of any separate wind and hail deductible, and whether an impact-resistant roof discount is offered. Your declarations page and endorsements answer all four.
How Soon After Hail to File
The right cadence:
- Within 24 hours: Document with photos and video. Tarp any active leaks.
- Within 1 week: Get an inspection from a local, licensed roofing contractor. Get their report in writing.
- Within 30 days: File the claim with your carrier. Earlier filings get more attentive adjusters before claim volume swamps the carrier.
- Within 6 months: Complete the work and submit final invoices to release recoverable depreciation (if RCV policy).
Filing immediately is almost always better than waiting. Storm-chasing contractors who tell you to “wait six months and I will file for you” are doing it for their own pipeline, not your benefit. Carriers do not punish prompt filers, and prompt filers get less scrutinized inspections.
Cost Math: What You Actually Pay
If your claim is approved at full replacement, here is what your numbers look like for a typical 2,000 sq ft architectural shingle roof in 2026.
| Item | Amount |
|---|---|
| Replacement Cost Value (RCV) estimate | $14,500 |
| Recoverable depreciation | ($3,500) |
| Actual Cash Value (ACV) initial payment | $11,000 |
| Less hail/wind deductible (1 to 3 percent of a $250,000 dwelling limit) | ($2,500 to $7,500) |
| Net first check | $3,500 to $8,500 |
| Second check after work completed (recoverable dep.) | $3,500 |
| Total carrier payout | $7,000 to $12,000 |
| Homeowner out of pocket (deductible) | $2,500 to $7,500 |
Hail and wind deductibles in storm-belt states are often separate from your standard deductible and run 1 to 5 percent of the dwelling coverage amount. On a $300,000 home, that is $3,000 to $15,000. Read your declarations page before storm season. For total project context, see how much does a new roof cost or run our roof replacement cost calculator.
Choosing a Hail Claim Contractor
The right contractor is local, licensed, insured, and has been in business in your area for at least 3 to 5 years. Avoid door-knocking storm chasers from out of state. Verify the contractor’s standing with the state contractor licensing board and with the BBB. Ask for at least 3 local references on past insurance work. See how to choose a roofing contractor for a full vetting checklist.
Frequently asked questions
How much hail damage to replace roof under State Farm?
State Farm does not publish the hit count its adjusters use. The 8 to 10 functional hits per 100 square feet figure is a widely cited rule of thumb, not a published State Farm or industry standard, and roof age, your policy form and state rules also affect the outcome. Ask the adjuster which threshold was applied and get the estimate and photos in writing.
Will insurance cover hail damage on an old roof?
Yes, if your policy is Replacement Cost Value (RCV) and the damage is from a covered storm. Roof age affects how depreciation is calculated but does not by itself void coverage. An Actual Cash Value (ACV) policy on a 22-year-old roof will pay much less than the same RCV policy, because depreciation eats the payout. Check your declarations page for “RCV” versus “ACV” on roof coverage.
How long do I have to file a hail damage claim?
It depends on your policy and your state. The policy’s “duties after loss” section sets the reporting deadline, and some states set one by statute: in Florida, notice of a new or reopened property claim must be given within 1 year after the date of loss (Florida Statutes section 627.70132). File immediately. Waiting reduces the carrier’s confidence that the damage came from the claimed storm.
What size hail damages a roof?
1 inch (quarter-sized) is the National Weather Service severe threshold and the practical floor for functional damage to standard architectural asphalt shingles. 1.25-inch hail will damage most non-impact-rated shingles. 2-inch hail damages every common residential roofing material to varying degrees.
Can hail damage a metal roof?
Yes, cosmetically. Metal roofs (especially aluminum and softer-gauge steel) can show dents from 1.5-inch and larger hail. Most dents are cosmetic only. Stone-coated steel and standing seam roofs perform best. Some carriers attach a cosmetic damage exclusion to metal roofs, which would bar a dents-only claim, so check your policy for one.
What happens if my deductible is more than the damage?
You pay out of pocket, and the claim closes with no carrier payout. If your policy has a percentage wind and hail deductible, it is a share of your dwelling coverage (2 percent of $300,000 is $6,000), so small to moderate hail damage can fall below it. Document the damage anyway. If multiple events happen in a year, the cumulative damage can sometimes be claimed together.
Will my insurance go up after a hail claim?
In most states, a single hail claim is treated as “act of God” and does not directly raise your individual premium. However, your carrier may raise rates broadly across the region after a major storm year. Some carriers also non-renew policies after multiple claims in a 3-year window. Filing one legitimate claim is rarely a rate-driver. Filing three is.
Should I get a Class 4 impact-rated shingle if I live in a hail belt state?
Often, but run the numbers first. Class 4 shingles usually cost more than standard architectural shingles, so get both prices in the same bid. Some carriers offer a premium discount for a Class 4 roof, and the amount varies by carrier and state, so ask your carrier for its figure and compare it with the extra cost. You also reduce the odds of needing to file a claim in the first place, which protects your renewal status.